Press releases
Quarterly Global 3D Printer Revenues Rise +31% YoY on Sustained Industrial Rebound and Unabated Entry-Level Momentum
A fourth consecutive quarter of growth for the Industrial 3D Printer market and tremendous Entry-Level shipments push total hardware system revenues up +31% year-on-year.
London, 13 October 2026 – Growth has decisively returned to the global additive manufacturing (AM) market, driven by skyrocketing demand for Entry-level systems and a massive capital investment supercycle in the high-end Industrial sector. According to the latest analysis by global market intelligence firm CONTEXT, total 3D printer hardware system revenues jumped +31% year-on-year (YoY) in the second quarter of 2026. Three of the four price classes saw higher unit shipment volumes in Q2 2026 than in the same period last year.
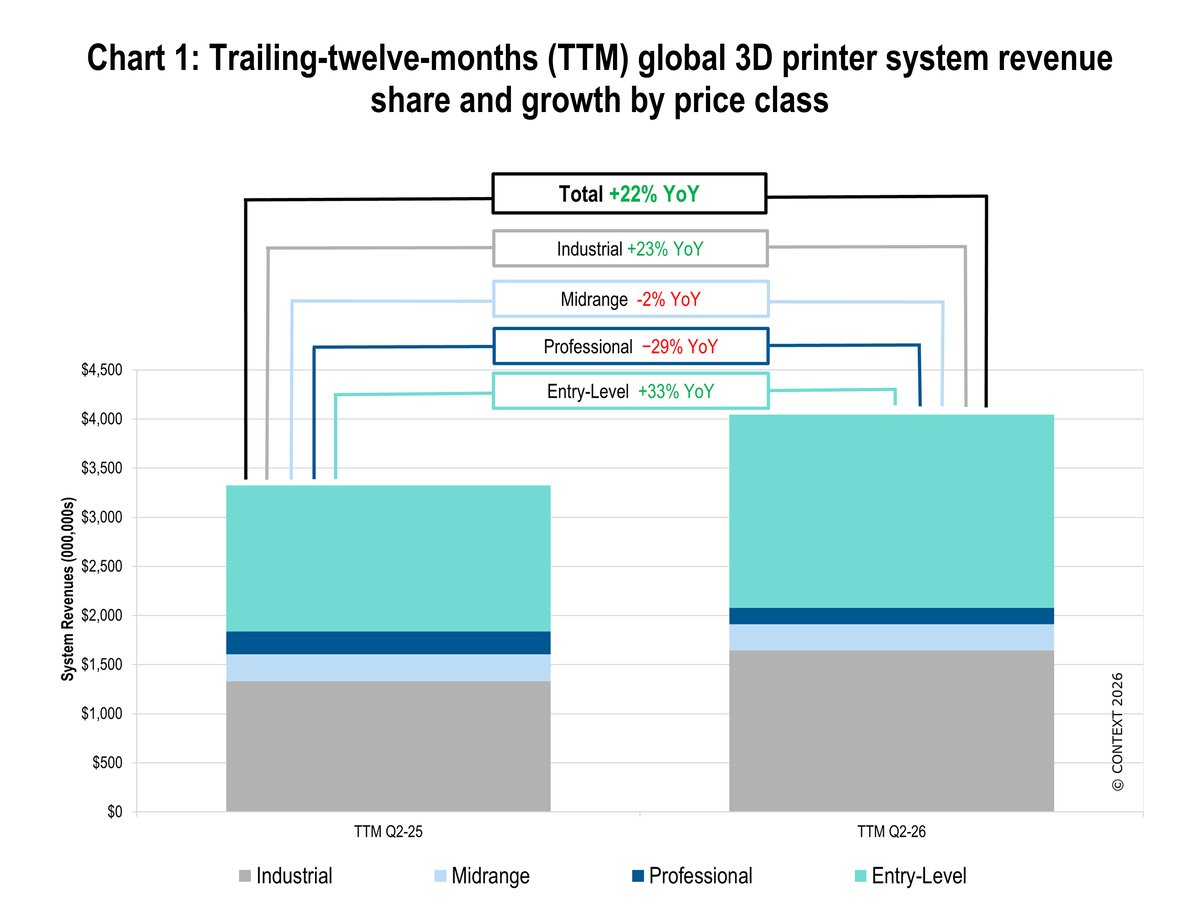
The Entry-level segment now represents the largest market share by value, accounting for 49% of all hardware revenues over the trailing twelve months (TTM), while the Industrial class accounted for 41%. Strong revenue growth occurred in both categories, with Industrial revenues rising +40% YoY in Q2 and Entry-level revenues climbing +36% YoY. TTM revenue growth reached +23% for Industrial and +33% for Entry-level systems.
Chart 1: Trailing-twelve-months (TTM) global 3D printer system revenue share and growth by price class
"There have been many catalysts for growth for 3D printing in the past, from specialized athletic shoes to pandemic supply-chain disruptions, but nothing quite compares to the current demand seen for the production of rockets, data center infrastructure, mobile consumer electronics devices and drones from across the globe presently," said Chris Connery, VP of Global Analysis at CONTEXT. "While Industrial 3D printing used to be defined by its use to produce hearing aids and clear dental aligners, in 2026, if you are manufacturing a drone, a rocket, or an advanced mobile phone, you are using 3D printing as an essential part of your manufacturing process."
Industrial Systems: Metals and Polymers Propelled by Defence, Aerospace, and 3C
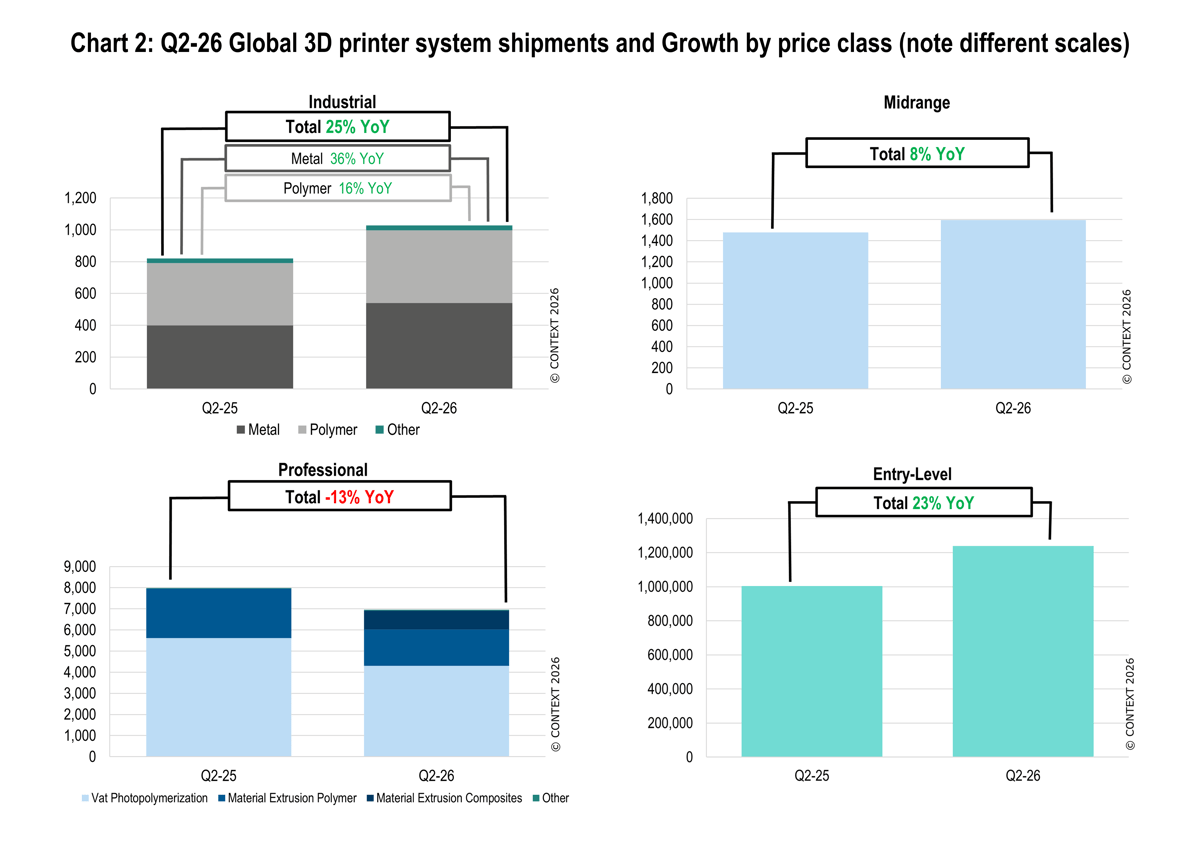
Unit shipments in the Industrial price class (>$100K) grew +25% YoY in Q2 2026, marking the fourth consecutive quarter of YoY growth. Global Industrial system revenues surged +40% YoY, propelled by robust demand across key global end-markets.
While China led total global Industrial shipments over the TTM with a 37% volume share (compared to 29% for North America and 21% for Western Europe), quarterly shipments into North America and China were nearly on par. Both key regions experienced sharp growth: North American Industrial shipments rose +44% YoY, while Chinese shipments grew +42% YoY. Regional supply dynamics remain distinctly localized for Industrial 3D Printer shipments, with Chinese vendors fulfilling domestic demand and Western OEMs supplying US and European customers.
-
Metals: Metal additive systems dominated the Industrial price class, accounting for 53% of unit shipments and 75% of total Industrial hardware revenue in Q2. Overall Metal printer shipments grew +36% YoY, while sector revenues jumped +51%. Powder Bed Fusion (PBF) remained the dominant technology, capturing 77% of Metal unit shipments and 83% of segment revenues.
-
Metal Highlights: Aerospace and Defence (A&D) served as the primary growth catalyst, particularly for Western OEMs. German market leader EOS achieved high double-digit revenue growth, supported by major A&D orders, including 30 Metal PBF printers for drone manufacturer Beehive Industries. Japanese-German vendor Nikon SLM Solutions also secured orders from Beehive for its ultra-large NXG 600E systems. The UK’s Renishaw doubled its Metal PBF shipments year-on-year, while US-based Arc Impact (owner of Desktop Metal) reported strong domestic defense demand. In China, Farsoon and BLT experienced strong first-half growth driven by the 3C (Computer, Communication, and Consumer Electronics) sector, where demand for titanium foldable phone hinges and smartphone frames surged.
-
Polymers: Industrial Polymer unit shipments increased +16% YoY globally. Growth was led by a +39% surge in Vat Photopolymerization shipments (driven primarily by UnionTech in China) and steady demand for high-temperature Material Extrusion systems. Stratasys secured significant domestic and APAC orders for its flagship F900 platforms. 3D Systems reported strong Q2 system sales with a positive Q3 outlook, highlighting its largest single order to date for Industrial Polymer systems destined for reusable rocket manufacturing. Additionally, HP secured an order from service bureau ADDMAN for 81 5620 MJF printers, expanding ADDMAN's total fleet to 125 units.
Chart 2: Q2-26 Global 3D printer system shipments and Growth by price class (note different scales)
Midrange and Professional Systems: Share Shifts and New Modalities
The middle price bands continue to face pressure from Entry-level systems cannibalizing traditional Material Extrusion (FDM/FFF) demand. However, technological shifts and industry consolidation are reshaping these segments.
-
Midrange ($20K–$100K): Global unit shipments rebounded +8% YoY in Q2 2026, while segment revenues rose +3%. The category is experiencing a structural pivot toward Polymer Powder Bed Fusion (SLS), which saw shipments jump +38% YoY. Further momentum is expected as Raise3D and others continue their rollouts alongside upcoming launches including Formlabs Fuse X1 and HP Jet Fusion 1200.
-
Professional ($2.5K–$20K): Unit shipments contracted -13% YoY and revenues declined -24%, impacted by ongoing weakness in legacy FDM systems. Despite headline declines, product innovation remains active. Shipments of Composite Material Extrusion systems commenced following FibreSeek's Kickstarter fulfillment, while Stratasys' pending acquisition of Markforged is set to further consolidate the composite sector. Additionally, lower-priced full-color Material Jetting platforms from vendors such as Flashforge (CJ270) and HeyGears (G1X) are expected to revitalize activity in upcoming quarters.