Small and medium-sized businesses across Europe
are changing where they buy IT hardware ahead of Q4. Resellers in
the Small and Medium Reseller (SMR) channel have traditionally
handled corporate upgrades. The August 2026 sell-out data from
CONTEXT Total Market suggests commercial buyers are turning more
often to retail chains for business notebooks.
Price is the most visible driver. In August, the
average selling price of a business notebook among SMR resellers rose
18% year on year to €860, from €730. Unit sales fell 15%, which held
revenue growth to just 1%.
Retail chains raised prices too, to €850 from
€725. They lost fewer units, with a 9% fall, and revenue rose 7%.
The average retail shelf price now sits €10 below the reseller average.
The data cannot say why buyers are moving, but
the explanation may lie in what retail offers: transparent pricing,
off-the-shelf availability and flexible purchasing terms. Retailers
stocking ready-to-use machines with professional operating systems,
robust chassis and enhanced security appear to be picking up sales
that resellers are pricing out of reach.
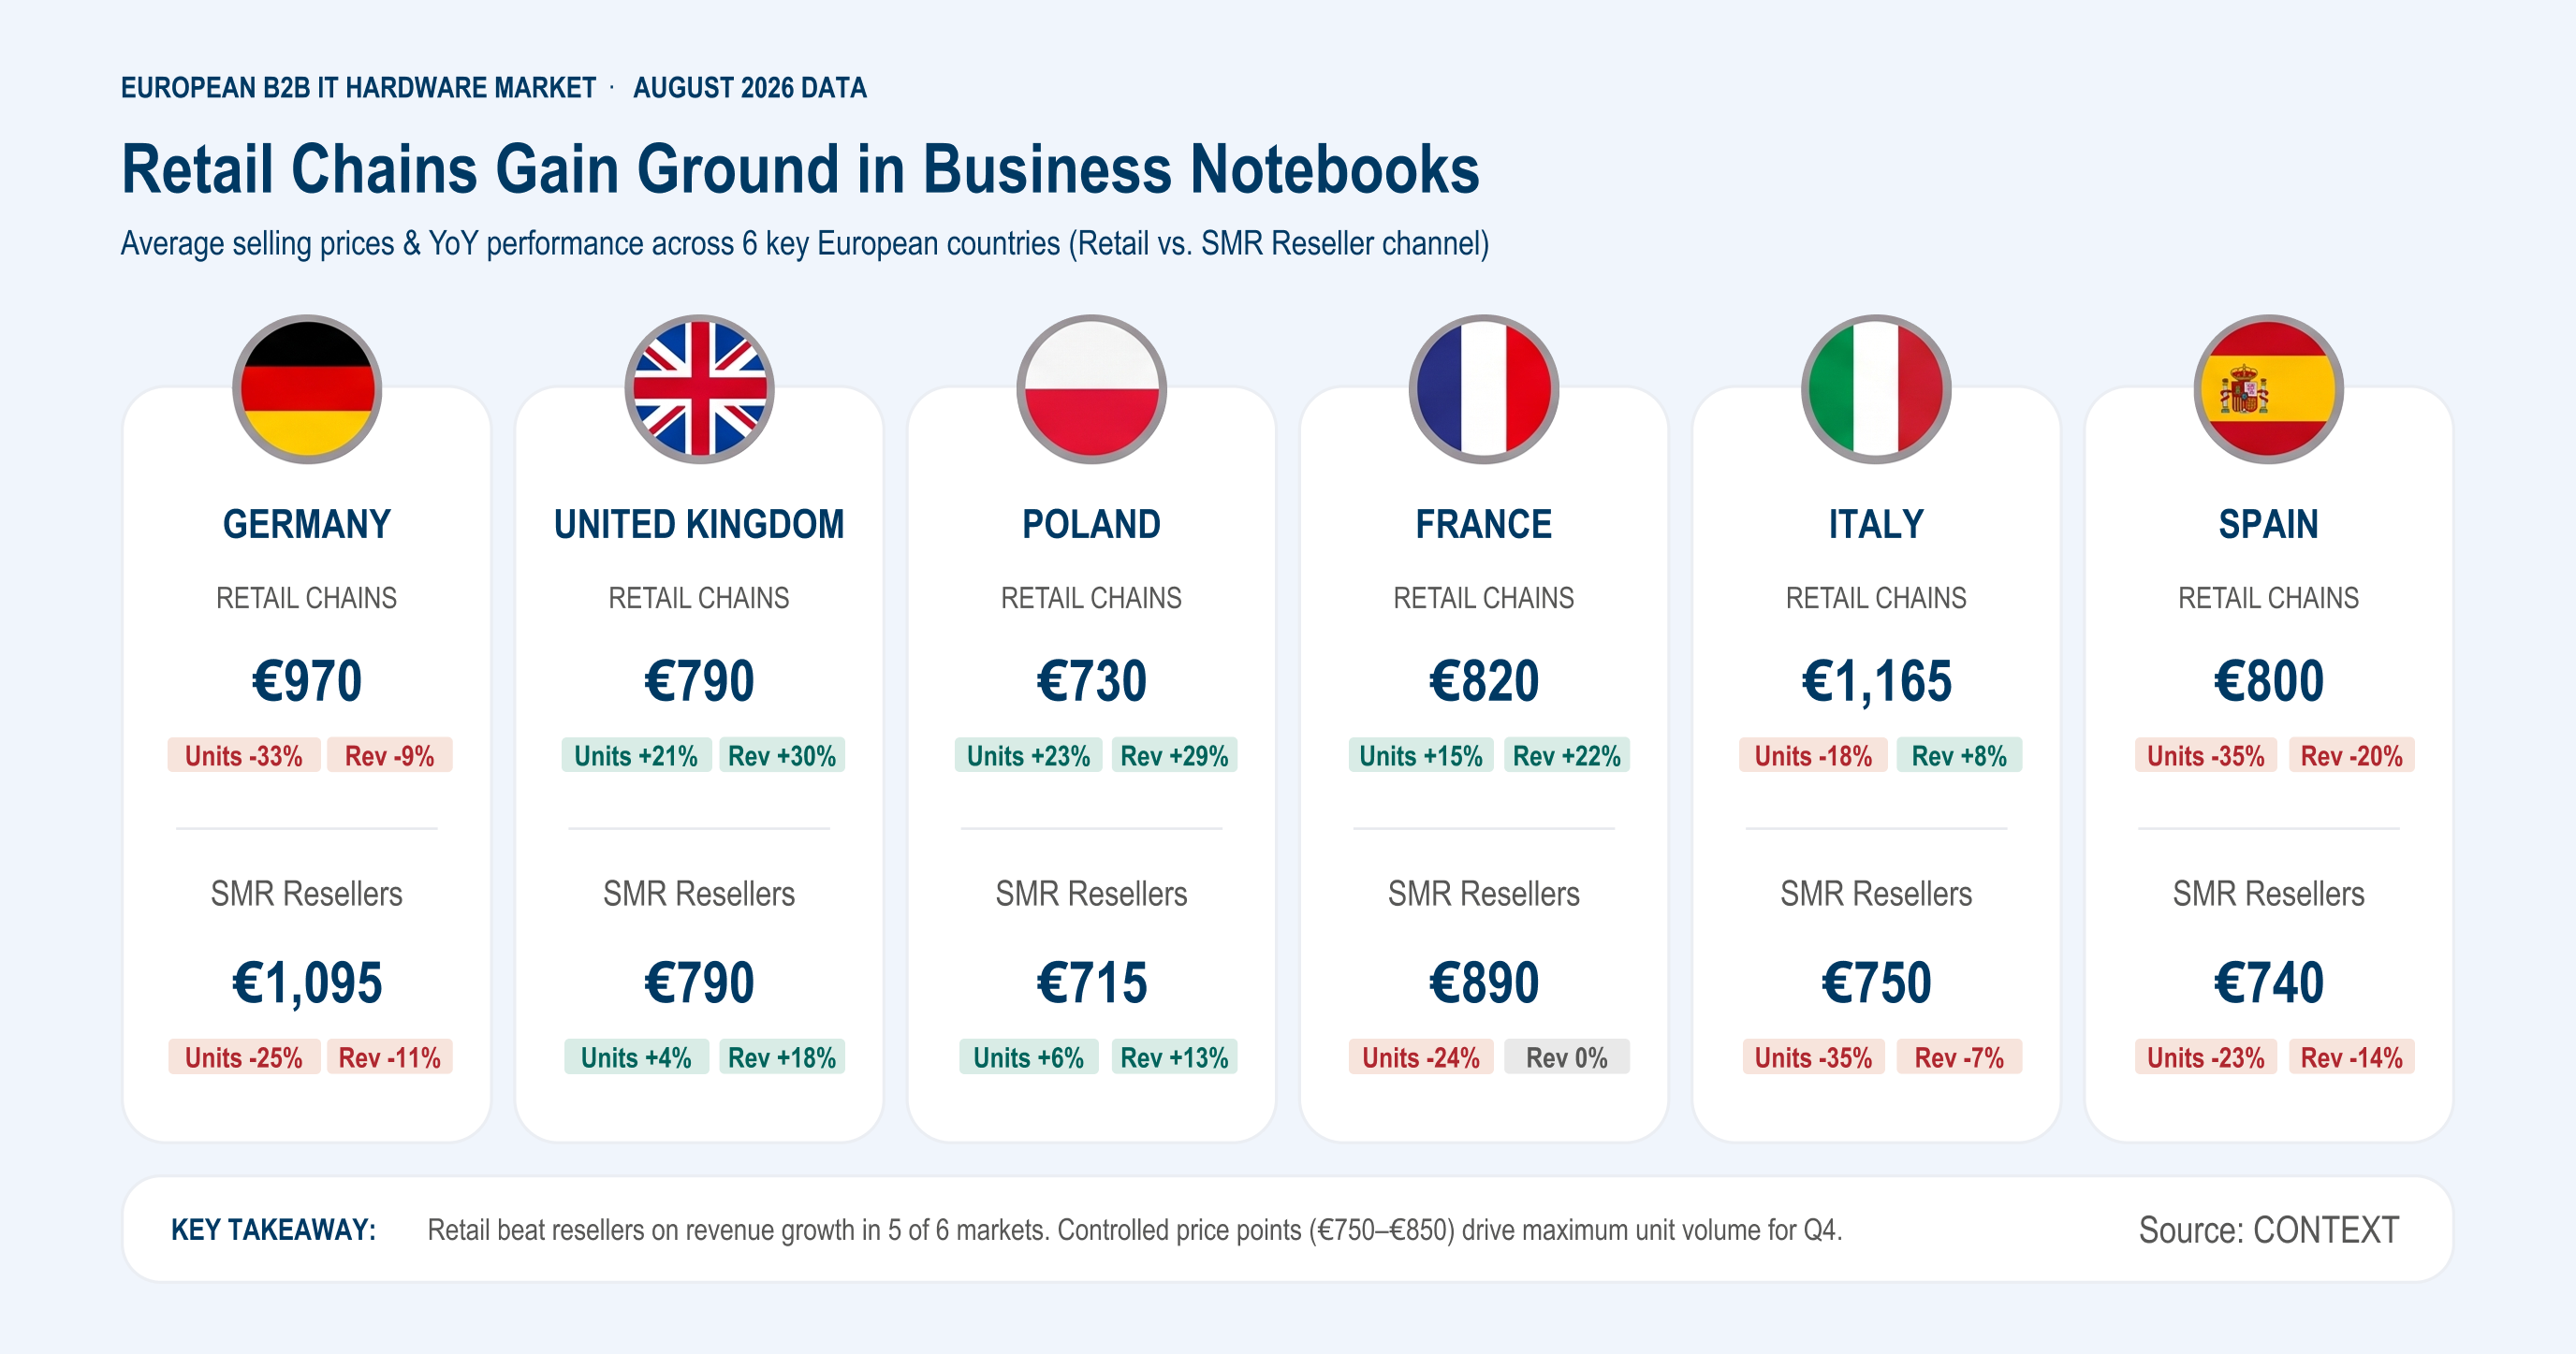
The picture is not uniform. Retail chains beat
resellers on revenue growth in five of the six markets, with Spain the
exception. On units, retail fell further than resellers in both
Germany and Spain.
Germany
High prices slowed the German market in August.
SMR resellers raised the average business notebook price 19% to
€1,095, from €920. Unit sales fell 25% and revenue fell 11%.
Retail chains fared slightly better on revenue
and worse on units. Their average price reached €970, up from €720,
and units dropped 33%. Revenue fell 9%.
German commercial buyers show clear resistance
above €1,000, and the retail average is close to that line. Sharp
promotional price points under €800 will probably be needed to bring
business buyers back in Q4.
France
French retail chains had a strong August. Revenue
rose 22% and units rose 15%, on a controlled price increase of 5% to
€820, from €780.
SMR resellers had a harder time. Their prices
jumped 31% to €890, units fell 24% and revenue was flat. Retail now
undercuts the reseller average by €70.
Retailers enter Q4 with momentum. Holding key
configurations around €800 should help them keep taking share from
traditional resellers.
United Kingdom
UK retail chains saw revenue rise 30% and units
rise 21%, with prices up a modest 7% to €790, from €740.
Resellers did well on revenue, up 18%, but their
unit gains were capped at 4% after prices rose 14% to €790. With both
channels at the same average price, retail took the larger share of
the volume.
UK businesses are buying actively when pricing
stays competitive. Offers in the €750 to €790 range look the most
likely to maximise Q4 volume.
Poland
Poland continues to lead European growth in
business notebooks. Retail chains lifted revenue 29% and units 23%,
with average prices up 5% to €730.
Resellers also expanded. Revenue rose 13% and
units rose 6%, at an average price of €715, up 7%.
Demand is healthy in both channels, so the main
task for retailers is stock. Depth in mid-tier models will matter more
than any change in pricing.
Spain
Spain went the other way. Retail revenue fell 20%
and units fell 35% after the average price rose to €800, from €655.
Resellers saw a similar decline, with revenue down 14% and units down
23% at €740, up 12%.
Spanish buyers are highly sensitive to price.
Rebuilding entry-level promotional tiers near €650, close to last
year’s retail average, will be vital for Q4.
Italy
Italian retail chains grew revenue 8% despite an
18% fall in units. A shift toward premium models lifted the average
price to €1,165, from €890. The revenue gain therefore rests on mix
rather than volume.
Resellers had a poor month. Their prices surged
44% to €750, from €525, units fell 35% and revenue fell 7%. The
increase may have alienated price-sensitive SMBs.
That leaves room for retailers with dependable entry-level
notebooks under €700.
What Q4 may bring
Across the six markets, the size of the price
increase seems to matter as much as the level. Where retail prices
rose 5% to 7%, as in France, the UK and Poland, units grew by between
15% and 23%. Where prices moved from €655 to €800 in Spain, or from
€720 to €970 in Germany, units fell by roughly a third.
Corporate year-end budgets are there to be won.
Keeping entry points within €750 to €850 looks like the practical way
to capture them and to sustain sell-through into the new year.
For weekly market updates and
analysis, join our Retail
Pulse Newsletter.