CONTEXT’s distribution sell-through data shows that notebooks with
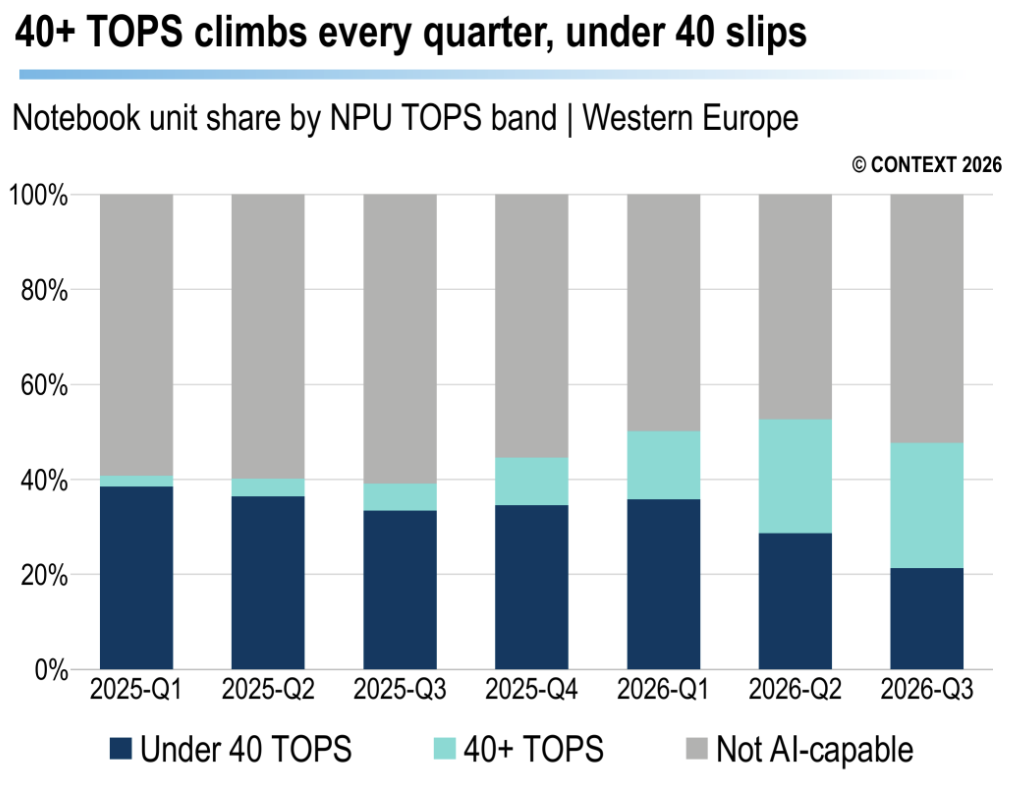
neural processing units (NPUs) rated at 40+ TOPS accounted for 26% of
notebook unit volume in Western Europe in Q3 2026, overtaking sub-40
TOPS models. Non-AI notebooks remained the largest segment, at 52%.
The figures show a shift towards higher-performance hardware, but
do not establish an equivalent increase in demand for AI applications.
What does 40+ TOPS mean?
TOPS stands for trillions of operations per second, a measure of
processing throughput. In this analysis, the 40+ TOPS category refers
to the notebook’s NPU, rather than its combined CPU and GPU
performance. The rating describes hardware capability, not actual AI
usage or business value.
How is the AI notebook mix changing?
CONTEXT’s Western European distribution data shows three key movements:
-
40+ TOPS notebooks: 26% of total notebook unit volume
in Q3 2026, up from 6% in Q3 2025.
-
Sub-40
TOPS notebooks: 21% in Q3 2026, down from more than 33% in Q1
2026.
-
Non-AI notebooks: 52% in Q3 2026,
retaining the majority of unit volume.
Higher-performance NPUs are gaining share within the AI-capable
category, while lower-performance configurations are losing ground.
Does higher NPU performance mean stronger AI demand?
Not necessarily. Processor refreshes can give buyers greater NPU
capability through routine notebook upgrades, without AI being the
main purchasing requirement.
A higher-TOPS sales mix is not, on its own, evidence of software
deployment, active AI usage or a proven return on investment.
Why do non-AI notebooks still matter?
Non-AI notebooks represented 52% of Western European distribution
volume in Q3 2026. That majority share makes them an important part of
channel portfolio planning.
Affordability, seasonal purchasing and product availability may
help explain the mix, but the aggregate figures do not establish their
individual effects.
Q3 2026 presents a mixed picture: higher-performance NPUs are
gaining share within AI-capable notebooks, while non-AI systems retain
the majority of unit volume. The shift in hardware capability is
clearer than any corresponding change in AI-led purchasing.
Source: CONTEXT distribution sell-through data, Western Europe.
Comparisons cover Q3 2026, Q3 2025 and Q1 2026. Figures refer to
notebook unit volume, not revenue.